Mortgage Servicers
Non-performing notes and REO aged past the point where a retail listing makes sense, including scratch-and-dent pools kicked out of prior trades.
Distressed single-family homes acquired from mortgage servicers, bankruptcy trustees, probate estates and foreclosure — from a single inherited house to a five-hundred-door portfolio, priced as one file and closed on our own balance sheet.
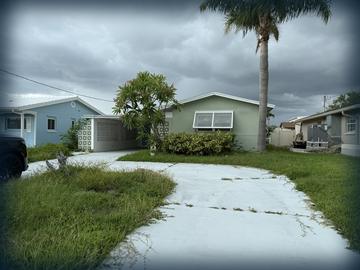
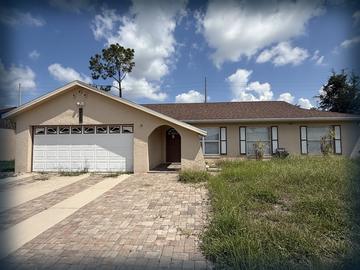
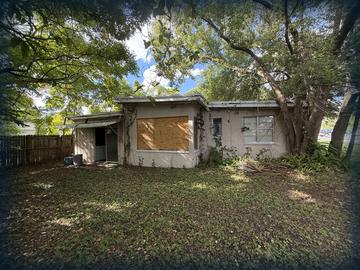
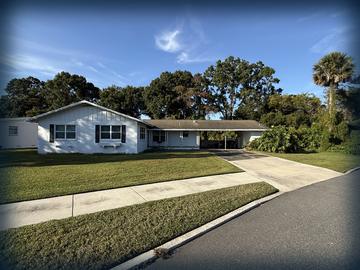
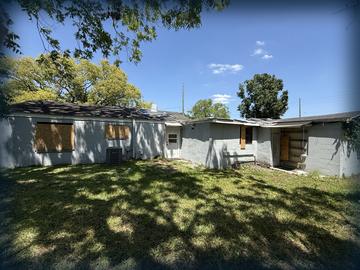
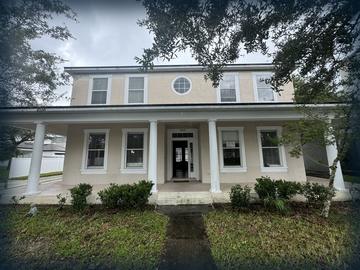
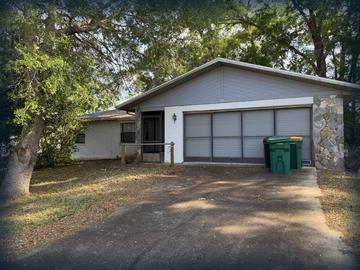
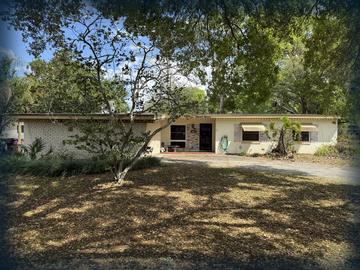
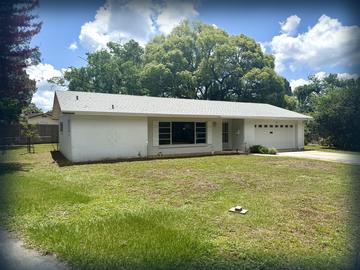
One inherited property in probate is enough. We buy single homes from heirs as readily as five-hundred-door pools.
Two business days on complete files. Incomplete tapes may require follow-up.
Subject to court confirmation, trustee approval and servicer timelines.
Each channel carries its own timeline, its own approval chain and its own way of going sideways at the closing table. We price title defects, occupancy and deferred maintenance in rather than excluding them — whether that is a five-hundred-door servicer pool or one house an heir inherited and cannot sell.
Non-performing notes and REO aged past the point where a retail listing makes sense, including scratch-and-dent pools kicked out of prior trades.
Chapter 7 and 11 estates where the trustee needs a buyer that will not walk and a timeline the court can rely on. Proof of funds delivered with the bid.
A single inherited house is enough — no minimum. Multiple heirs who cannot agree, deferred maintenance, contents still in the home, and sales conditioned on court confirmation.
Pre-auction files where a sale beats the calendar, post-sale positions inside a redemption window, and occupied assets requiring lawful possession work.
Delinquent tax certificates, code enforcement and municipal liens, judgments and mechanics liens. Clouded title we cure rather than price around.
Landlords exiting a full rent roll in one transaction instead of thirty separate closings. Tenants in place, leases assumed as written.
HUD auctions pools of defaulted, formerly FHA-insured reverse mortgages. In every loan the last surviving borrower has died, no non-borrowing spouse survives, and the heirs never paid off the debt. Winning the pool is the straightforward part — what follows is probate, title and occupancy work running across dozens of states at once.
That is the work we already do. We take assets off your pool as principal, on our own balance sheet — including the tail your model excluded and the states your servicer will not travel to — so your capital rotates instead of sitting in a workout.
Vacant one-to-four-unit properties securing HECMs where the last borrower is deceased. Bought as-is, cleanout included.
Occupied by non-borrowers — surviving family, heirs in residence, tenants. Possession resolved lawfully, or we take the asset occupied.
An unsettled estate clouds title on every asset in the pool. We run probate and quiet-title work in house rather than pricing around it.
HVLS purchasers report dispositions to HUD. Exits can be structured as owner-occupant sales or affordable rentals where pool commitments require it.
We publish what we learn from the same sources we underwrite against — HUD's Office of Asset Sales post-sale reporting, Federal Register sale notices, and Federal Reserve series. Each piece is sourced and dated.
Peter Quinones has joined the National Association for Housing Revitalization among its founding class, taking a role in the association’s policy and advocacy work as federal law begins to reshape who is permitted to buy single-family housing.
Read → Policy analysisThe headline is that Congress banned institutional investors from buying houses. The statute is narrower, later and stranger than that — it does not start until January, it does not count mortgage debt, and it contains a foreclosure carve-out that will decide how the next few HUD loan sales are bid.
Read → Policy analysisA new federal law bars large institutional investors from buying single-family homes. HUD now asks bidders to attest that the loans they buy will not end in a purchase the law prohibits. The threshold is 350 homes — and in the last vacant sale, one buyer took 309 loans in a single afternoon.
Read → Bidder analysisTwenty-two buyers took 1,061 loans. Two of them took nearly half. One paid 18 cents on the broker’s dollar. And the spread of those loans across the map says more about what happens next than the prices do.
Read → Policy analysisThere has been a decisive shift in who buys HUD's distressed reverse mortgage pools. Mission-driven nonprofits took 4% of the loans before 2019; they now take a majority of some sales. If you bid on these pools, or buy assets from the firms that do, this is the most consequential change of the last five years — and it is a policy decision, not a market one.
Read → Pricing benchmarkThe short answer is 69.4% of broker price opinion. That is what 1,061 defaulted reverse mortgages sold for in HUD's most recent vacant loan sale — roughly sixty-nine cents against the estimated value of the houses securing them. But the way that number is reported is easy to misread, and the spread underneath it is where the real information sits.
Read → Industry guideThe first thing to understand is that HUD is not selling houses. It is selling defaulted loans — specifically reverse mortgages where the borrower has died. The house comes later, once whoever bought the loan forecloses on it. That single distinction explains most of what confuses people about this market.
Read → Seller's guideIf you are holding distressed single-family assets and need them gone, the hard part is rarely finding someone who says they buy distressed property. Plenty do. The hard part is that the phrase covers buyers whose minimum size differs by a factor of a thousand, and whose willingness to take an occupied house with clouded title differs by everything.
Read →
Most buyers want a clean file: vacant, marketable title, a cooperative seller. That leaves a large amount of American housing stuck in probate court, in a trustee's inventory, or on a servicer's books for years.
We underwrite the complication instead of excluding it. Because we take the whole file rather than cherry-picking it, sellers get one transaction and one closing date instead of a slow bleed of individual sales and broken escrows.
We buy with our own capital. We are the principal, not a middleman marking up your file.
We confirm once. Pricing is not reopened asset by asset after the bid is accepted.
Files are reviewed internally and never circulated to other buyers, brokers or list vendors.
Analysis of the distressed single-family market, built on primary data from HUD and the Federal Reserve.
Investor Trustee Services acquires and resells real property for its own account. Nothing on this site is an offer to sell or a solicitation of an offer to buy any security, nor is it investment, legal, tax or accounting advice. We do not act as a fiduciary, trustee or custodian for any third party. All acquisitions are subject to diligence, title review and a definitive written agreement.
Bid turnaround and closing timelines shown on this site are typical and depend on court confirmation, trustee approval, title curative work and servicer processes we do not control. Door ranges, response times and closing periods are targets, not guarantees.
Program descriptions and definitions are drawn from the FHA Office of Asset Sales. Investor Trustee Services is not affiliated with, endorsed by, approved by, or acting on behalf of HUD, FHA, or any transaction specialist engaged by them. Chart figures represent unpaid principal balance and loan counts as announced by HUD for each sale — amounts offered, not sale results. HNVLS 2026-1 was postponed from its February 2026 bid date. Source: hud.gov/hud-partners/housing-asset-sales
Indicators shown are retrieved from FRED, Federal Reserve Bank of St. Louis. The 30-year fixed rate average is published by Freddie Mac and reproduced with citation as required. Single-family mortgage delinquency is published by the Board of Governors of the Federal Reserve System. Months' supply of new houses is published by the U.S. Census Bureau and HUD. Figures are updated periodically and may lag current market conditions.